
Canadian Charity Registration and Revocation Statistics 2026
Published on
October 14, 2026
Last updated on
October 14, 2026
TL;DR: CRA revoked 2,076 charity registrations in 2025–26. Failure to file the annual T3010 return caused 1,219 of those revocations (58.7%). ITA s. 149.1(14) requires that return within six months of fiscal year-end. Only 52 revocations (2.5%) were for cause. On the registration side, CRA approved 79.2% of charity application outcomes in 2025–26. Its current service standard is a final decision on 80% of complete applications within nine months. [9][16]
Who should read this report?
This report is for treasurers, secretaries and board chairs of registered charities, especially the volunteers who are personally responsible for filing the T3010. Most charities that lose registered status do so because a return was not filed, not because of misconduct.
This report is also for founding boards preparing a charity registration application who want realistic approval odds and timelines. It covers CRA's published figures from 2015–16 through 2025–26. Fiscal years end March 31.
What do the key terms mean?
- Registered charity: an organization CRA has registered under the Income Tax Act. It can issue official donation receipts and is exempt from income tax (ITA s. 149(1)(f)).
- Qualified donee: an organization that can issue official donation receipts (ITA s. 149.1(1)). Registered charities are the largest group. CRA's recent reports count charities and other qualified donees together.
- Revocation: CRA cancels registered status. The organization can no longer issue receipts.
- Voluntary revocation: the charity asks CRA to cancel its registration, often because it is closing or merging.
- Notice of intention to revoke (Form T2051A): CRA's formal notice that it plans to revoke.
- T3010: the Registered Charity Information Return every charity must file each year.
- Eligible donee: a charity that can receive a revoked charity's assets without triggering revocation tax.
What are the key findings for 2025–26?
What percentage of charity registration applications does CRA approve?
CRA approved 79.2% of charity application outcomes in 2025–26, down from about 81.9% in 2024–25. [8][9] Outright refusals are rare: CRA found only 19 applications ineligible, under 1% of outcomes. Most applications that are not approved fail for avoidable reasons: they are incomplete, abandoned or withdrawn.
A dash means the figure was not captured for this comparison.
For applicants, the lesson is direct. The biggest factor an applicant controls is a complete, consistent application: governing documents, charitable purposes, activity descriptions and financial information. See how long it takes to register a charity in Canada and our CRA charity application checklist.
How fast is CRA approving charity registrations in 2026?
CRA's current service standard is a final decision within nine months of receiving a complete application, 80% of the time. [16][17] Two words matter:
- "Complete" means the clock starts only once CRA has everything it needs.
- "Final decision" includes refusals, not only approvals.
CRA has not yet published a result for this new measure. [9][16]
The earlier standard measured something smaller: an initial response within six months, which could be a request for more information. CRA met that target in every year from 2019–20 to 2024–25 except 2020–21, when the result was 62%. [10–15]
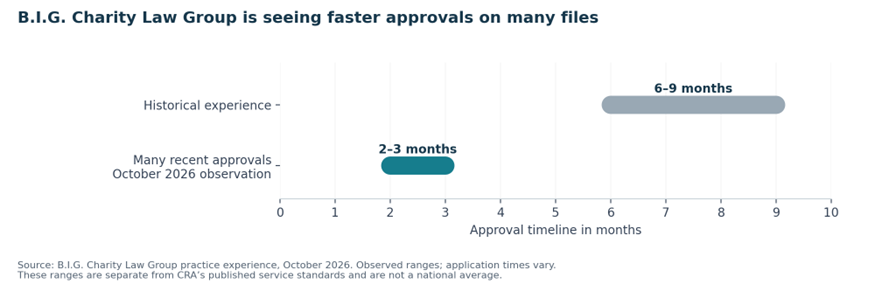
[Figure 1: initial-response results, 2019–20 to 2024–25]
In our charity registration practice, as of October 2026, many straightforward applications are being approved in about two to three months. Before, we commonly saw six to nine months. This is B.I.G. Charity Law Group's observation, not a CRA measure or a national average. CRA's 2025–26 report credits simplified workflows and earlier decisions on incomplete or ineligible applications for improved timeliness. [9]
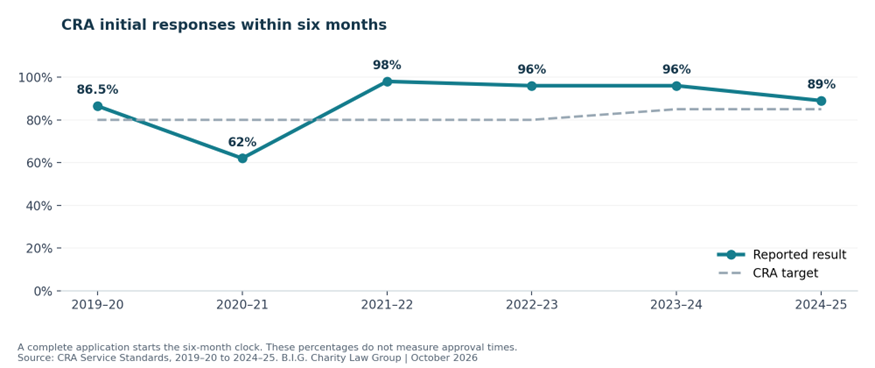
[Figure 2: firm-observed approval ranges]
How many registrations does CRA revoke each year?
CRA reported an average of 2,090 revocations a year from 2023–24 to 2025–26. Reported revocations rose 45.3%, from 1,429 in 2015–16 to 2,076 in 2025–26. Reporting scope differs across years, so this compares the two end years only. It does not prove a steady rise. [1][9]
A dash means the figure was not separately reported, not zero. The 2018–2020 report gives no annual totals for 2018–19 or 2019–20. "For cause" groups CRA's historical "for cause / after audit" labels. Sources: [1]–[9].
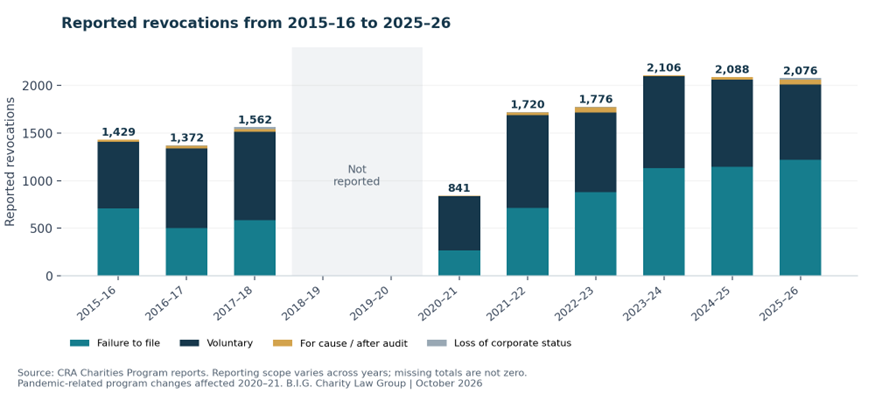
[Figure 3: revocation counts, 2015–16 to 2025–26]
Why does CRA revoke registered status?
Failure to file the T3010 is the leading cause of revocation, at 58.7% of all revocations in 2025–26. [9]
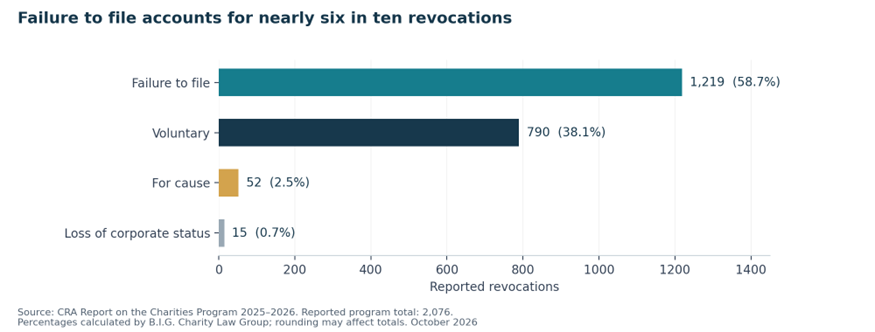
[Figure 4: reasons for revocation, 2025–26]
A revocation total is not a measure of wrongdoing. Voluntary revocation is at CRA's discretion and cannot be used to avoid ongoing compliance action. [18]
For-cause revocations doubled from 26 to 52. However, notices and revocations can fall in different fiscal years, so one year's jump can reflect older files closing.
Are failure-to-file revocations rising?
Yes. Total revocations have been flat for three years, at 2,106, 2,088 and 2,076. Over the same period, failure-to-file revocations rose from 1,131 to 1,219, up about 8%. Voluntary revocations fell from 966 to 790. [7][8][9]
A growing share of revocations is avoidable. These charities did not choose to close; they missed a filing deadline.
What happens when a charity misses its T3010 deadline?
CRA follows a set statutory process. Once the formal notice arrives, the charity has 90 days to fix the problem. [18][19]
Revocation has three main consequences:
- Receipting stops. The organization can no longer issue official donation receipts.
- Tax exemption ends. The organization may become taxable, unless it qualifies as a non-profit organization under ITA 149(1)(l).
- Revocation tax applies. Under ITA 188(1.1), the tax can equal the full value of remaining assets. This applies to assets not spent on charitable activities or transferred to an eligible donee within the winding-up period. The organization must file Form T2046 within one year of the T2051A notice date. [18]
What should charity boards do to protect registered status?
Boards should treat the T3010 deadline as a fixed governance obligation with a named owner. Six in ten revocations come from missed filings, so these steps cover the largest risk:
- Name one director or staff member responsible for the T3010 each year.
- Set an internal deadline at least 60 days before the six-month due date.
- File online through My Business Account and keep the CRA confirmation with the board minutes.
- Treat any T2051A as urgent. The 90-day window is the last chance to cure.
- Review corporate annual filings too, since loss of corporate status also triggers revocation.
See our annual checklist for charity boards and guide to charity revocation. If you need help preparing the return itself, B.I.G. Charity Accounting Firm handles T3010 preparation.
Frequently asked questions
How long does a charity have to file its T3010?
A registered charity must file its T3010 within six months of its fiscal year-end (ITA 149.1(14)). For a December 31 year-end, the return is due June 30. [19]
Can a charity stop a revocation after receiving a notice of intention to revoke?
Yes, in most failure-to-file cases. The charity has 90 days from the T2051A notice to file a complete T3010 or a written objection. After that, CRA can confirm revocation with a T2051B. [18]
Is CRA approving charity registrations faster in 2026?
CRA's standard is a final decision on 80% of complete applications within nine months. In B.I.G. Charity Law Group's practice, many straightforward applications are now approved in two to three months. That is a firm observation, not a CRA statistic. [16]
What percentage of charity applications does CRA approve?
CRA approved 79.2% of charity application outcomes in 2025–26, and fewer than 1% were refused as ineligible. Most of the rest were incomplete, abandoned or withdrawn. [9]
What happens to a charity's assets after revocation?
Some assets are not spent on charitable activities or transferred to an eligible donee within the winding-up period. Revocation tax applies to those assets under ITA 188(1.1), and the tax can equal their full value. [18]
Can a revoked charity register again?
Yes. The organization must submit a new application through CRA's My Business Account. CRA generally expects outstanding returns and any revocation tax to be resolved first. See our guide to reinstating a revoked charity.
How were these statistics calculated?
Revocation and application figures come from CRA's Report on the Charities Program series. Timing measures come from CRA's annual service-standards pages. Recent reports count charities and other qualified donees together. The totals are therefore reported Charities Program figures, not a charity-only series.
Annual means are the arithmetic mean of published totals. Percentages use each year's total and are rounded to one decimal place. Missing years are excluded, not counted as zero.
Sources
[1]–[5], [7] CRA, Report on the Charities Program, 2015–2016 through 2023–2024 (keep existing links)
[6] CRA, Report on the Charities Program 2022–2023
[8] CRA, Report on the Charities Program 2024–2025
[9] CRA, Report on the Charities Program 2025–2026
[10]–[14] CRA, Service Standards, 2019–20 through 2023–24 (keep existing links)
[15] CRA, Service Standards 2024–25
[16] CRA, Service Standards 2025–26
[17] CRA, Service Standards 2026–27
[18] CRA, Types of revocation
[19] CRA, Filing a Registered Charity Information Return: When to file
[20] Income Tax Act, R.S.C. 1985, c. 1 (5th Supp.), ss. 149(1)(f), 149(1)(l), 149.1(1), 149.1(14), 168, 188
This report provides general information and is not legal advice for a particular organization. For help with an application, a T2051A notice or a revocation, contact B.I.G. Charity Law Group Professional Corporation. Our charity governance and compliance services support boards with ongoing filing obligations. For last year's analysis, read our review of CRA's 2024–2025 Charities Program report.
The material provided on this website is for information purposes only.. You should not act or abstain from acting based upon such information without first consulting a Charity Lawyer. We do not warrant the accuracy or completeness of any information on this site. E-mail contact with anyone at B.I.G. Charity Law Group Professional Corporation is not intended to create, and receipt will not constitute, a solicitor-client relationship. Solicitor client relationship will only be created after we have reviewed your case or particulars, decided to accept your case and entered into a written retainer agreement or retainer letter with you.
DOV GOLDBERG, J.D. is a lawyer at B.I.G. Charity Law Group and has dedicated his career exclusively to Charity and Not-for-Profit Law for over a decade. Dov guides charities, foundations, and non-profit organizations through every stage of the registration process, offering practical legal advice with a focus on compliance, governance, and long-term success. Known for his hands-on approach and deep knowledge of CRA requirements, Dov is committed to helping clients build strong, sustainable, and legally sound organizations.


